Every Man, Woman and Child in Guyana Must Become Oil-Minded – Column 130 – June 14, 2024

Exxon’s incredible (and unique) return on Equity

Introduction

This week’s column features the financial statements of the Guyana branch of ExxonMobil Guyana Limited, a 45% stakeholder, and the designated Operator, in the Stabroek Block. In what was a first for any company in Guyana, the financials, part of a wider report, were presented at a  media event hosted by the branch President Mr. Alistair Routledge. The very colourful cover pages mirror the annual report of the US parent, in appearance, content and excitement, except that the parent’s report flaunts metrics like earnings, shareholder distributions, return on average capital employed and annualised total shareholder returns. Perhaps with only mild exaggeration, the US parent report states that its work in Guyana continues to be among Exxon’s most exciting and successful – for its business, the people of Guyana, and the world. Exxon has brought prosperity to the world – truly a unique blessing.

In the case of the Guyana branch, it is about what the Deus ex Machine, our great white knight, has done for Guyana, including the 1,700 “unique” Guyanese companies which supply Exxon’s operations, the thousands of Guyanese individuals it employs, its contribution to the Natural Resource Fund, the monies invested in communities across Guyana, and the volume of business it brings Guyanese suppliers. Even when Exxon acknowledges the country’s natural resources, it takes the credit for the successful optimisation of those resources. To use its own words, “it is not that Exxon is merely extracting resources; [they] are expanding the potential of the nation.” Halleluiah!

Income statement

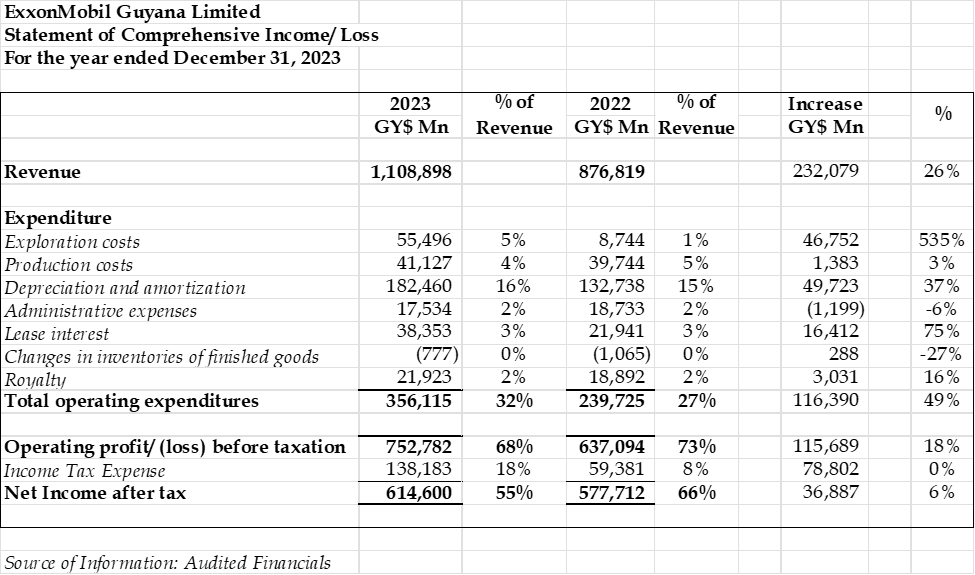
While its blurbs and Fast Facts confuse and mislead, no doubt deliberately so, the performance of the Guyana operations in 2023 is probably without industry equal. Revenue has moved from $876,819 Mn. to $1,108,898 Mn, an increase of 26% while its operating profit has moved from $637,094 Mn. to $750,782 Mn., an apparently more modest 18% increase. But that is largely due to the fact that this reckless government allows the Exxon and its co-venturers to use part of our share of profit to explore for new finds as the date for exploration comes to an end in 2027. It may sound harsh, but it is hard to think of anything more absurd and violative of Guyana’s interest.

Another astounding measure derived from the financials is the negligible production cost which in 2023 accounted for a mere 4% of revenue, down from 5% in 2022. In fact, the only cost which accounts for more that 10% of revenue is Depreciation and Amortisation, accounting for 16% of revenue. Lease interest, an accounting rather than an actual expenditure, is stated at $38,353 Mn., a 75% increase over 2022. This increase is due to a $206,777 Mn. addition to Drill Rigs.

The fake tax charge

After all actual and other expenses, the branch reports Operating Profit before tax of $752,782 Mn., an increase of $115,688 Mn., or 18.2% increase. The Income Statement which is summarised below shows a charge for taxation of $138,183 Mn. and it is only when one looks at Note 7 to the financial statements does one realise that the so-called tax expense is actually paid by the Government of Guyana – another unique feature of our oil arrangements. By now, we all know that there is no charge to the company, which not only walks away with the full amount of $752,782 Mn., but also with a receipt issued by the Guyana Revenue Authority which Exxon then uses to obtain a tax credit from the US Government. Without raising anything about exemption from withholding tax which is required to be paid by ordinary companies on distributions and interest, the actual money that Exxon walks away with is the $752,782 Mn. plus a tax receipt for $138,183 Mn., making a total of $890,965 Mn! In a single year.  
Balance Sheet

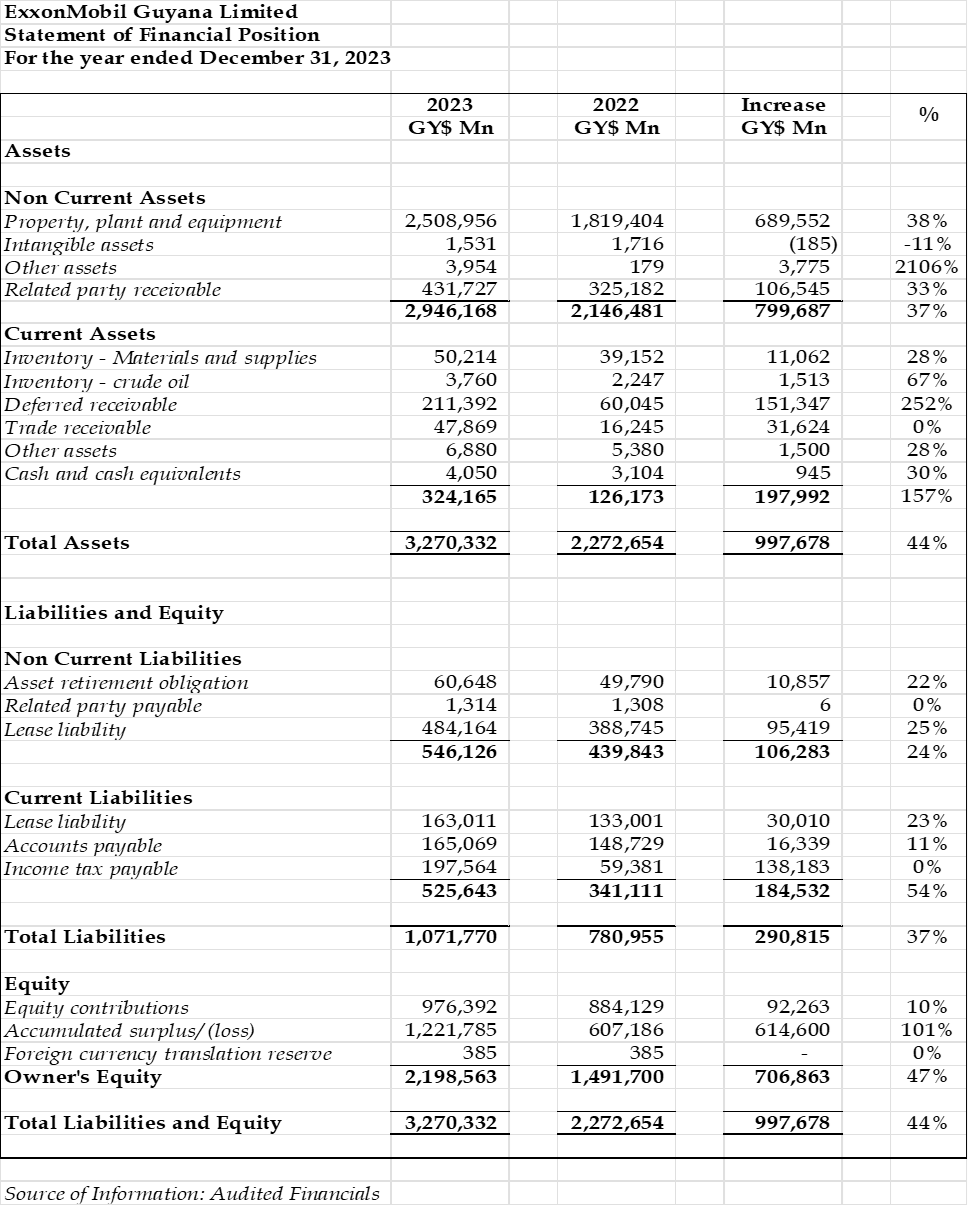
Total assets of the branch at the end of 2023 was $3,270,332 Mn., an increase of $997,678 Mn., or 43% over 2022. As is evident from the Summary Balance Sheet extracted from the branch’s audited financial statements, there were significant increases in Property, Plant and Equipment; Other Assets which had a 2,106% increase; Inventory of crude oil; and Deferred Receivable. The notes to the financial statements (found on chrisram.net) show that of the assets acquired, 35% were on lease but accounted for as additions, to meet accounting rules. It is worth noting that the item of asset with the most significant increase (Other Assets) is not supported by any explanatory note and is therefore uncertain. Like HESS, this branch also shows a significant closing inventory of crude oil, which is at least surprising, since their sales are more than likely within the Exxon family. Deferred Receivable increased by 252% but the only elucidation offered in the accompanying Notes is that the amount of $211,392 Mn. includes non-customer receivables. Interestingly, that includes the Tax Recoverable from the Government of Guyana – all part of an accounting myth.

Total liabilities of $1,071,770 Mn. represents a 37% increase over 2022 but here too, some of these arise out of accounting convention, such as Lease Liability and Income Tax payable which is totally misleading if not grossly incorrect. Accumulated Surplus at 31 December 2023 of $1,221,785 Mn. reflects an increase of $614,600 Mn. which is the amount of profit after (fictitious) taxation of $138,183 Mn.

Exxon’s contribution

By its own admission, and stripped of all its contrivances, the true value of the investment in the branch at 31 December 2023 is stated in the line item Equity Contributions as $976,392 Mn. The note explains that “Equity contribution relates to amounts paid into the Branch by its head office.” In other words, the return on average equity of $930,260 Mn. is a unique 96%! And we must not forget that the Branch’s Head Office was the architect of the fraudulent inflation of its pre-2015 costs and the diversion – in violation of the 2016 Agreement – of moneys received from Hess, CNOOC and Shell (twice), for their investment in the Stabroek Block.

Despite all these shocking revelations, disclosures and discoveries, our Oil Czar sees the 2016 Agreement as inviolable, sacred and untouchable. His only objection is that Exxon does not share the kudos for oil’s bonanza with him. Anyone who places the sanctity of a hugely questionable and lopsided contract above sovereignty is no better than the fool who signed the contract in the first place.

These results and the audited financial statements of Exxon and its two joint venture partners render as nonsense the proposition that Guyana and the oil companies are in a 50/50 partnership. This must surely be the petroleum equivalent of the Stockholm Syndrome.
Every Man, Woman and Child in Guyana Must Become Oil-Minded – Column 129 – June 7, 2024

Introduction

On 29th December 2023, in a letter to the press, I argued that the Natural Resource Fund was overstated by G$274 BN., the amount of the Corporation Taxes paid by the Government on behalf of the oil companies required under Article 15.4 of the 2016 Petroleum Agreement. Attorney General, Mr. Anil Nandlall, S.C., disputed my assertion in a direct, unnamed tirade against me.

Mr. Nandlall wrote that the supremacy provision (section 45) of the Natural Resource Fund Act overrode the provisions of the 2016 Petroleum Agreement, boldly asserting that the provisions in the Agreement on taxation have “obviously been overtaken by the Natural Resource Fund Act”.  In the process he completely ignored the Stability Clause of the Agreement, which requires the Government to pay the taxes of the Oil Companies out of its share of oil revenues. What is indisputable is that despite the so-called supremacy clause, the Government continues to pay the taxes for the oil companies.

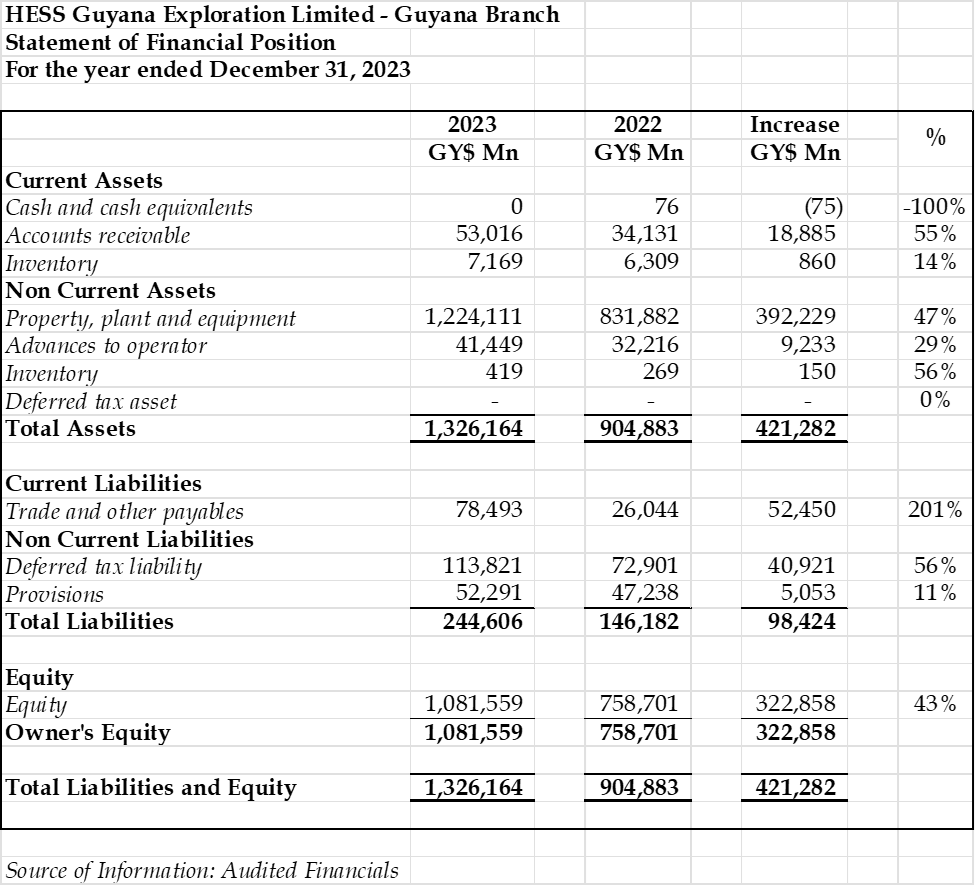
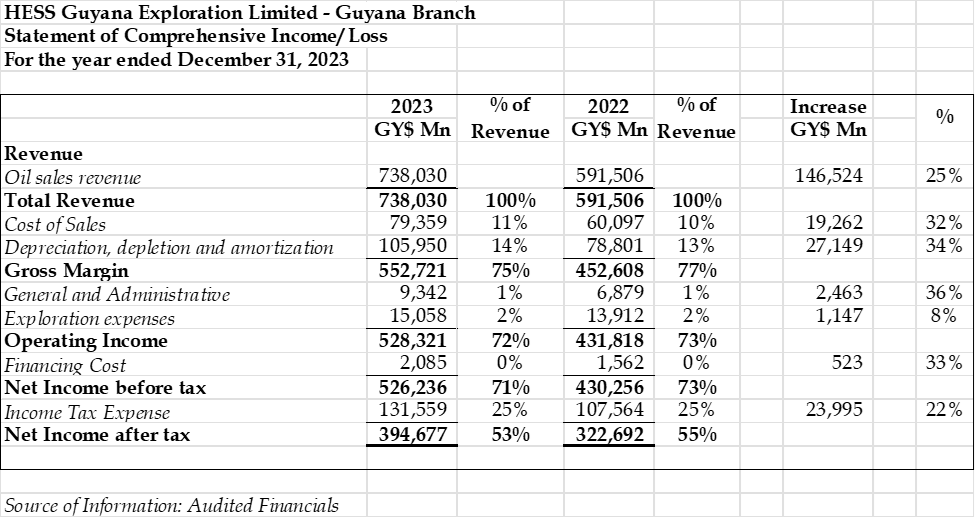
The 2023 financial statements of Hess, a 30% partner in the Exxon-led joint venture show a tax charge of G$131,559 million, or approximately 22% more than 2022. The Note to the financial statements shows that the charge includes Deferred Tax of $40,920 million. More significant than the 22% increase is how the tax charge measures up against the profit oil earned by Guyana for the whole of 2023. From figures available on the BoG website, the total tax charge is about 45% of the country’s earnings from profit oil earned by Guyana for the whole of 2023.

Let us have a look at how Hess performed. Its oil revenues grew to $738, 030 million, an increase of 25%, compared with an 8% decline in the Hess International group as a whole. In fact, all the key financial indicators for Hess in 2023 were down, compared with 2022. No wonder then that Guyana is likened to the Indo/British Kohinoor, the jewel of the Hess’ crown. It would be surprising if that comparability is significantly different in the case of Exxon and CNOOC.

 Cost of Sales for the Guyana branch grew by 32% over 2022 but remained constant as a percentage of revenue. Cost of sales is made up principally of Operating Cost and expenses and Royalties and whether and how useful this is as a predictive value is uncertain. Oil companies are generally expert at aggressive tax planning and even now, the financial statements disclose depreciation, depletion and amortisation at some 163 per cent of operating costs and expenses. This latter group of expenses in 2023 (13% of revenue), but a 34% increase over the preceding year. Because there is no ringfencing, exploration expenses are charged against income, but at 2% of revenue, even the dollar amount is not particularly significant. 

The Balance sheet

The growth in the total assets over 2022 is a significant 47% which is identical to the growth in Property, Plant and Equipment, shared between Exploration and Evaluation Assets (21%) and Development Assets (79%). Because of the uncertainty associated with such expenditure, Exploration and Evaluation Assets are not depreciated. Depreciation expenditure on Development Assets account for 99.9% of Depreciation charge for the year.

Exxon

Maybe it is purely by coincidence, ExxonMobil Guyana invited the domestic press for a briefing on its own 2023 audited financial statements and apparently to offer some guidance on how the press should report on financial matters. Whatever its motives, the company should be complimented on this display of accountability even as it has refused to answer questions concerning its own suspect accounting for moneys received from various entities.  

Next week’s Road to First Oil will review the company’s 2023 financial statements which reflect a bonanza year for the company.  

Every Man, Woman and Child in Guyana Must Become Oil-Minded – Column 128 – May 24, 2024

Insurance and its adequacy (Part 3 final)

Introduction

The two previous parts on this subject carried on Monday (20th.) and Wednesday (22nd) dealt with the first of two documents published in the Official Gazette a week earlier. These were the Guarantee and Indemnity Agreements by the oil companies with the Guyana Government as the beneficiary, and an Insurance Policy taken out by the oil companies for the year 2024 – 2025. Since these are not documents required under any circumstances to be published in the Official Gazette, it is unclear why they appear in a medium reserved for official publications which describes itself as “Published by the Authority of the Government.” In fact, every one of the pages of Exxon’s Insurance Policy carries the heading Official Gazette! No stopping Exxon and the overwhelming influence of American Power.

Let me state one caveat: Insurance is a very specialised branch of law and is well known for its complexity and its “fine print” which challenges even the most meticulous reader. One characteristic of insurance policies is that the exceptions and exemptions are usually so many that they narrow the scope of coverage significantly, of which the Policy contains ample evidence. Maybe we can take comfort that the Ministry of Natural Resources, in exercising its oversight role, will regard the Policy as an area of interest to which particular interest needs to be paid.

Contract of Insurance

Today’s column deals with the second document – a 159-page Contract of Insurance issued by insurance giant AON UK Limited, considered among the top three insurance brokerage firms in the world, its reputation expertise covering all stages in the oil and gas sector. Exxon boasts of its contribution to the local economy but not a penny, not a dime, not a nod to local content. The premium on the Policy is not cheap – about US$5 Mn. Had the oil companies not been given blanket exemptions from all taxes – for forty years no less – this payment would have been subject to a withholding tax under the Income Tax Act. So, we lose on local content and local tax.

The choice of law and the jurisdiction for the Policy are the Courts of England and Wales. Although the cover page of the Policy gives prominence to ExxonMobil Guyana Limited as the Insured, the details show that its partners Hess and CNOOC, all covered to the extent of their respective interests in the Guyana operations. The Policy runs from 1st. February 2024 – 19th. February 2025 but there is strong evidence that this may be an extension of a previously existing policy.

The Policy extends limited coverage beyond the three companies, to a broader group of related entities and individuals, subject to specific policy provisions and more narrowly defined limitations. The individuals include employees, consultants or contractors. These collective entities and individuals are covered under the policy for various risks, including environmental liabilities, physical damage, and third-party legal liabilities.

The Policy contains a mix of coverages and exclusions that directly address certain environmental liabilities, especially seepage and pollution from wells and other insured property, while limiting or excluding pollution coverage in other respects.

Some arcane details

The Policy appears to offer sufficient coverage for moderate incidents, but clearly not for any major events. Interestingly, coverage under the Policy is substantially below asset values as shown in the financial statements of the three companies, perhaps betting that no single accident or occurrence would reach anywhere close to US$2.5 Bn. However, the real costly occurrence would be in respect of any spill arising from any accident at any of the wells.

Concerns about oil spills in the Stabroek Block are eminently justified, both as regards the operations, supervision, and oversight: the Block has an elevated level of petroleum activities in a fairly concentrated area; an ever-present potential for accidents, mishaps, human error, equipment failure and stress; and the complexity of the operations.

To put things in perspective, the Gulf of Mexico covers an area of 617,000 square miles while the Stabroek Block covers just over 10,000 square miles – one-tenth. Yet, on an area comparison by barrels of oil per day, Guyana can soon outperform the Gulf of Mexico. But that will come at a cost. Unlike the USA, The Gulf operators have had decades of experience operating in those waters and the sector is effectively managed, overseen by experts and strict laws, professionally and independently enforced.

Guyana’s totally contrasting circumstances contribute in no small measure to increasing overall fears and risks. We have seen numerous examples of poor oversight of the sector, preference for loyalty over competence, and the Government’s inability to recognise that the country needs to see more than just money from the sector.

Conclusion

It is time that President Irfaan Ali realise that Vice President Bharrat Jagdeo does not have the time, inclination or expertise for the challenge at hand. That incredibly, the regulation of the sector is on autopilot, if not self-regulated. The President must realise that there is no substitute for a properly constituted Petroleum Commission with a range of skills and experience. And that on the environment, it is naïve and reckless to believe that as currently staffed, the EPA can exercise any form of control over the oil companies. The President should see this both as a historic opportunity and an imperative that he needs to act before it is too late.

The US$2 Bn. guarantee might have been expected to silence the din. But it is no substitute for unlimited Parent Companies guarantees.

Every Man, Woman and Child in Guyana Must Become Oil-Minded – Column 127 – May 22, 2024

Insurance and its adequacy (Part 2)

Introduction

Yesterday’s column addressed three Guarantee and Indemnity Agreements (GIA) granted by the oil companies to the Environmental Protection Agency. These we are told, is to provide some assurance to Guyana that there is money available to deal with any environmental events or accidents arising from petroleum operations under the 2016 Petroleum Agreement.

On environmental matters, petroleum operations in Guyana must be conducted in accordance with the requirements of that Agreement, and the Environmental Permits issued to the oil companies under the Environmental Protection Agency Act (EPA). It must not be forgotten too that the 2016 Agreement was issued under the Petroleum Exploration and Production Act of 1986 (PEPA) which has its own Regulations, also addressing environmental issues. Not surprisingly, however it is the EPA came some ten years after the PEPA which is the main environmental protection and regulation statute. And just for completeness, the Constitution has elevated the citizens’ right to an environment that is not harmful to his or her health or well-being – a negative right rather than a positive right to a healthy environment.

The EPA

The EPA was passed in 1996 and was probably then in line with international best practice. The problem is that that was twenty-eight years ago, and the law appears to have been frozen in time. The official copy of the Laws of Guyana shows that except for a single amendment in 2005 there has been no modernisation of the legislation since its passage. That is a most unfortunate state of affairs, and one must wonder why no Government since the discovery of oil has thought it necessary to review the legislation. What we are stuck with therefore, is an Act that is out-of-date, and which is administered and enforced by an under-resourced and under-qualified management.

The 2016 Agreement

Because the 2016 Agreement enjoys a forty-year stability, it is perhaps the first place we need to look. In summary, this is what the Agreement provides.

  1. The oil companies must obtain an environmental authorisation from the Environmental Protection Agency and comply with the Act, for any activity governed by the Act. Generally, the geographical area over which activity is allowed and the scope of the activity would be set out in the Permit.
  • The oil companies must take necessary and adequate precautions to prevent pollution and protect the environment and living resources in rivers and sea. “Living” in this context will include flora and fauna, such as birds, animals, plants.
  • If non-compliance with its obligations results in pollution or environmental damage, the oil companies must take reasonable measures to remedy the situation and treat or disperse the pollution in an environmentally acceptable manner. However, the Contractor is not obligated to remedy pre-existing pollution or environmental damage.
  • Where there is an emergency or accident arising from Petroleum Operations, the Contractor must notify the Minister immediately and take prudent and necessary actions in accordance with good international petroleum industry practices. If the Contractor fails to control or clean up pollution within a reasonable period specified by the Minister, the Minister may take necessary actions after giving notice to the Contractor and pass on not actual costs but reasonable costs and expenses to the Contractor.

Now, this is where the Agreement looks asinine – is it realistic to expect the Government to find the resources, negotiate the terms and contract some third party to come and sort out the problem or disaster while the oil companies sit back and contact their lawyers?  This also places the US$2 BN. in some relief. As noted in yesterday’s column, drawdown from the Indemnity Agreement is not automatic, and the Government will have to carry out a series of preliminary tasks. Of course, one needs to be realistic: a spill will have serious effect on the stock price of the oil companies which is always their first consideration. Altruism, self-interest and reputation protection will push those companies into high gear to deal with the disaster.

It’s the risk, stupid.

But that brings us back to the US$2 BN. While the probability of an oil spill may seem low, there are so many things that can go wrong – an electrical fire, an explosion, equipment failure, ship’s collision, etc. More importantly, this is not only about the probability of an accident but also the consequences of that eventuality.

The US$2 BN. might have been a direct result of pressure from certain quarters of society, but that itself raises several questions. While Article 28 of the Agreement seems to cast the responsibility new far and wide, the Indemnity sub-clause 2.4 provides some express limitations, as follows:

Liability by the Contractor to the Government for damages in respect of Petroleum Operations under this Agreement is limited to insurance required in accordance with Article 20.2 (a), provided however, that the Contractor shall not be liable to the Government for indirect, punitive or consequential damages, including but not limited to, production or loss of profits.

But Article 20.2 (a) seems to be wider, not narrower, than Article 2.4. It requires the Contractor to effect at all times, insurance of such type and sums customary in the international petroleum industry and not limited to loss or damage to all assets used in Petroleum Operations; pollution caused in the course of Petroleum Operations for which the Contractor or the Operator may be held responsible; and loss or damage to property or bodily injury suffered by any third party.

Self-insure

But here is the catch. The oil companies have the right to self-insure with the permission of the Minister. There is no indication from their financial statements that the oil companies are self-insured, and it appears therefore that the companies are in breach of their obligations under Article 20.2 (a) for which the Guarantee and Indemnity Agreement is not a substitute. 

It is evident that this whole question of insurance, guarantee and indemnity is a mess. Hopefully, there is an adult somewhere in the room who understands the Petroleum Agreement, is not compromised, and who is courageous enough to stand up for Guyana. Will that person please get to work and resolve this confusion.

This Friday, I will address the 159-page Insurance Contract.  

Every Man, Woman and Child in Guyana Must Become Oil-Minded – Column 126 – May 21, 2024

Every Man, Woman and Child in Guyana Must Become Oil-Minded – Column 126 – May 21, 2024

Insurance and its adequacy (Part 1)

Introduction

The Official Gazette of 11 May 2023 published two documents – a Guarantee and Indemnity Agreement  dated 9th. June 2023 (GIA) and a Contract of Insurance effective 1st. February 2024. The first deals with the Environmental Obligations of the three Contractors – Exxon, Hess and CNOOC – and the second, with third party insurance taken out by the companies to protect against a range of risks to their assets and operations. The beneficiary under the GIA is the Environmental Protection Agency while the beneficiary under the Contract of Insurance is the oil companies themselves.  

The 39-page GIA is made up of three separate but identical Agreements in which the Guarantors – all affiliates of the oil companies – undertake on behalf of the three Contractors to indemnify the EPA as the beneficiary on behalf of the Guyana Government.

Here is a table of the respective GIAs.

Oil CompanyShareGuarantor  Jurisdiction
Hess Guyana Exploration Limited30%                  Jamestown Ins. Co. Ltd.                       Bermuda  
CNOOC Petroleum Guyana Limited           25%                  CNOOC Limited           Hong Kong
Esso (E & P) Guyana   Limited45%          Exxon Equity Holding Company               Delaware (USA)            

G$2 BN not adequate 

The maximum total sum payable under the three GIA is US$2 Bn., less than bird feed in relation to the average US15 Bn. cost of the last five international environmental disasters. Given the number of wells in simultaneous production in relatively close proximity to each other in the Stabroek Block, the risk of things going wrong increases exponentially.

The 2016 Agreement repeats identically the Indemnity provision of the 1999 Agreement, which was already overgenerous to the oil companies, on more than just royalty and taxation. If the GIAs are all the country can insist on in relation to environmental insurance, then Guyana is dangerously exposed. Any spill can spell disaster, wiping out the Natural Resources Fund in one stroke.  

In every case, the GIA is guaranteed by an affiliate of the respective oil company. In identical wording, the three GIAs assure that the Guarantor is rated by an internationally recognised credit rating agency. It seems that the EPA forgot to ask the name of the credit rating agency, the actual rating. The lawyer representing the EPA should feel extremely uncomfortable about this omission.

 In any case, it is doubtful whether the Agreements meet the requirement of the environmental permits which require Exxon as the Operator, to provide to the EPA legally binding undertakings of adequate financial resources for the Co-Venturers to pay or satisfy their respective environmental obligations regarding the Stabroek Block if their respective Co-venturers fail to do so. A total $2 BN for the three companies is far short of adequate.

The centerpiece of the Environmental Obligations is in respect of any pollution or other harm to the environment caused by petroleum operations in the Stabroek Block. These include the cost to prevent, reduce or contain the discharge or release of any contaminant; any monetary fine or penalty imposed by the government; and any damages arising from failure by the oil companies to comply with lawful directions given by the EPA. 

Bearing the real burden

Drawing down from the GIA is not automatic and will probably be costly since the EPA will have to bear all legal costs incurred by it in enforcing or attempting to enforce the guarantee. To do so, it must first show that there has been a default; that the oil company has failed to discharge its environmental obligation; that the amount does not exceed the sum guaranteed in respect of that oil company; and that the EPA intends to draw down under the Agreement. In strict legal language, the Agreement provides that the Guarantor shall have no liability for any indirect, special, consequential loss, loss of profit or punitive damages arising from or relating to the guarantee and Indemnity Agreement, or the transactions contemplated. The consequences of these exceptions fall squarely on the country.

Suspicion

It is rare for finance companies operating in three different jurisdictions to  have identically worded legal documents, or to have a choice of law in favour of a developing country with only a partially developed legal system. What is unprecedented is to have each of these three Agreements signed on the same day, across three different time zones, in which one signatory is common – that of the EPA head. It is unclear what legal advice the EPA took in negotiating and signing these complex documents, or why the Agreements have no subscribing witnesses, or why all the pages are not initialed as good practice requires.

There is a sneaking suspicion that these Agreements were put together with an eye on the case brought by citizens seeking to have such an agreement produced in court. The three companies have been evasive and possibly dishonest along the way, as the matter wended its way to the CCJ. Courts look with disfavour at such conduct. Something seems wrong that Exxon Guyana is now a major user of an expensive, overburdened court system to which it contributes nothing and extracts every drop of blood and ounce of flesh. Oh, and to have a state agency pay the cost of publishing their documents!    

In a column on Wednesday of this week, I will compare the Guarantee and Indemnity Agreement under the environmental laws with the 2016 Agreement.