The 2026 Mid-Year Report states that NIS received about $24.5 billion in the first half of the year against expenditure of $21.9 billion. Those figures suggest a healthy current cash flow but say little about the condition of a social-insurance fund whose obligations extend decades into the future. That is why the law requires periodic actuarial assessment.
Days later, portfolio Minister Dr. Ashni Singh told NIS’s 57th anniversary observance that contributors must not be “pushed around,” that complaints had declined and that the Scheme should be judged by whether people receive the benefits to which they are entitled. He also cited nearly 80,000 additional contributors since 2020 as evidence of progress.
But that figure too needs context. In the oil economy, many contributors are temporary or short-term workers, some remaining in Guyana for only a few months. They may contribute at relatively high levels but leave before qualifying for, or ever claiming, benefits under the Scheme, let alone an old-age pension. Numbers without context can therefore materially overstate what the increase means.
That is precisely why contributor growth, by itself, tells us so little about the health of NIS. The Scheme must be judged over the long term – by its actuarial sustainability and, by Singh’s own test, by whether contributors actually receive the benefits to which they are entitled.
Let us see how Singh’s test has worked for two literally long-suffering individuals.
Craig and Zainul
Nathan Craig is 81. He worked for Kaieteur Company Limited and later Linden Mining Enterprise Limited and paid more than the 750 contributions required for an old-age pension. NIS rejected his claim. He appealed in September 2010 and waited thirteen years before the Appeal Tribunal ruled in his favour in October 2023.
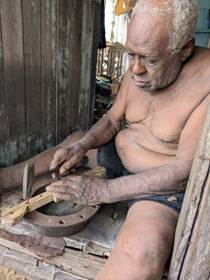
NIS then appealed to the National Insurance Commissioner. The problem was that there was no Commissioner in office. Craig had followed the statutory process, waited more than a decade and won, yet still could not reach finality because Government had failed to maintain the office required for the next stage of appeal. At 81, Craig remains unpaid and does small manual jobs to earn a dollar here and there.
Shariff Zainul’s case is different but equally disturbing. Contributions were deducted from his wages, but substantial amounts were not remitted. NIS produced changing contribution totals and rejected evidence supporting his claim. The High Court ordered that 354 disputed contributions be credited and that his pension be paid from age sixty. The Full Court later set that decision aside and sent the matter back for rehearing.
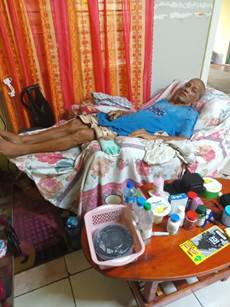
Fifteen years after reaching pension age, Zainul still has no pension and is now confined to bed. I sent the President a photograph of his condition; there has been no response. The bitter irony is that Zainul continues to bear the consequences of NIS failure, while the employer whose non-remittance helped create the problem appears to have suffered none. I have at least fifteen other NIS matters awaiting a meeting requested two months ago, including one involving a contributor repeatedly travelling from the UK simply to have contribution records merged.
The actuarial record
The National Insurance and Social Security Act requires actuarial review of the Fund at least every five years. The Eighth Actuarial Review, as at 31 December 2011, warned that the Scheme was approaching “crisis stage,” even as earlier recommendations remained unimplemented. By 2016, NIS itself acknowledged that more than 70 recommendations had accumulated from actuarial and reform exercises. The 2023 audited financial statements still carried serious actuarial concerns about the Scheme’s long-term position.
In effect, NIS has accumulated recommendations far faster than it has implemented them. Over the past two decades, the Scheme would be hard-pressed to identify even one significant actuarial recommendation implemented for each year that has passed.
Responsibility extends beyond any one Minister. Dr. Singh bears responsibility for substantial periods during which NIS fell within his portfolio, but so do successive Governments, Boards and managements. The reviews were done and the warnings given. The failure was to act.
Nor can Dr. Singh’s stewardship be separated from the CLICO episode. As Finance Minister in 2009, he told Parliament that NIS had about $5.6 billion invested in CLICO, roughly 20% of the Scheme’s assets. That exposure later had to be dealt with through a government debenture arrangement under the Coalition. The episode should have reinforced the need for stronger investment governance, risk management and institutional reform.
An institution showing its age
The NIS began operations in September 1969, as a pioneering social-security institution, but fifty-seven years later too much of the Scheme still reflects the era in which it was created.
Its contributor and beneficiary populations have expanded enormously, yet its principal facilities remain inadequate. As recently as 2016, NIS itself acknowledged that staff were working in “less than acceptable conditions,” while it was developing online contribution checking, electronic employer schedules and programmes to cleanse contribution data. (National Insurance Scheme) Former General Manager Patrick Martinborough documented how deeply administrative and record-keeping weaknesses became embedded in the Scheme.
Zainul’s case demonstrates the consequence. Defective contribution records are not merely untidy files; they can determine whether a person receives a pension. After so many years with responsibility for NIS, Dr. Singh cannot plausibly treat these as inherited administrative defects. Their persistence is part of his own stewardship.
The pension and the grant
NIS states that the old-age pension must not be less than 50% of the existing Public Service Minimum Wage. The published minimum pension is $43,075, while the current Public Service minimum wage is $102,346, making 50% $51,173.
On NIS’s own published rule, every pensioner receiving the minimum is therefore shortchanged by $8,098 per month. The latest published Annual Report does not tell us how many pensioners receive the minimum, so the total cost cannot be calculated precisely. But for every 10,000 such pensioners, the annual shortfall is about $972 million.
Government meanwhile promoted one-off grants to contributors falling short of the 750 contributions required for a pension, on a “full and final” basis. The 2025 Budget extended that arrangement to persons with 500 to 749 contributions. I argued instead for a pro-rated pension, so that someone contributing for ten, twelve or fourteen years would retain some income for life rather than receive a cheque that eventually disappears.
I am tempted to describe the policy cynically as a combination of the Mahdia Dormitory model: instead of curing the underlying problem, offer a lump sum in full and final settlement and close off the claim, while presenting the intervention as generosity. The circumstances are obviously different, but the administrative instinct is familiar – settle the claimant rather than repair the system.
The irony is hard to miss. Government publicised one-off payments with one hand while the minimum pension appears to have fallen below NIS’s own benchmark with the other. The grant was once only; the pension shortfall recurs every month.
And the $10 billion?
In his 2025 Budget Speech, Dr. Singh said Government would be “injecting $10 billion into the Scheme” to finance the full-and-final grants – subject to claimants forgoing their legal rights. NIS, however, says it received only periodic reimbursements for grants actually paid, and that total payments under the programme fell far short of $10 billion. Yet the 2026 Estimates show virtually the entire $10 billion provision as revised expenditure for 2025.
Taken together, the pension shortfall, the full-and-final grants and the supposed $10 billion injection begin to resemble a fiscal three-card trick. The cards now need to be turned face up: how much was actually paid in grants, how much was reimbursed to NIS, how much is owed to minimum pensioners under the 50% rule and, if virtually the whole $10 billion was recorded as spent, where did the balance go?
NIS and accountability
The latest annual report currently published on the NIS website is for 2023. There is none listed for 2024 or 2025. For an institution whose solvency depends on contributions, investments, demographics and future benefit obligations, reporting years behind is unacceptable.
Nor can failure to lay a report in Parliament justify keeping existing information from contributors and the public. Accountability also requires functioning statutory offices, reliable records and public reconciliation of the $10 billion.
Perhaps the larger failure is that Guyana has changed dramatically while the Scheme has changed far too little. A modern NIS should be capable of addressing gender-neutral parental benefits, unemployment protection and some form of medical support for elderly pensioners. The old legislation, old buildings, old systems, old records and old benefit architecture cannot simply be carried indefinitely into a new economy.
Patrick Martinborough warned that national insurance must change with its environment if it is to remain relevant. The actuaries have repeatedly identified the weaknesses and prescribed reforms. Dr. Ashni Singh now tells NIS that contributors must not be pushed around and that the test is whether they receive the benefits to which they are entitled. For my part, I have been advocating changes to national insurance since the late 1970s, including working with trade unionists Nanda Gopaul and Lincoln Lewis.
The voices have therefore not been absent. Nor have the diagnoses. What has been missing is sustained action – particularly by Ashni Singh and the PPP/C.
There is little in the record to suggest that this column will have any greater impact on the NIS administration or the Government than the actuaries, Martinborough and others who have warned before it.
And that is the true tragedy of the NIS.
Christopher Ram, wrote Grenada’s National Insurance Act and Regulations and served as the first Chairman of its National Insurance Board.