Ashni Singh criticizes Transparency International methodology

Introduction
December 9 was an important day for Guyana. For the first time since 2003 when the United Nations designated the day as International Anti-Corruption Day to raise awareness about corruption as an international and domestic agenda issue, the day was marked with a public activity – a seminar – in which the Government of Guyana took part. While President Ramotar could not be present his administration was represented by re-appointed Finance Minister Dr Ashni Singh who made a full-length presentation on behalf of the government, and Ms Gail Teixeira.

The event was sponsored and hosted by Transparency Institute Guyana Inc and its directors succeeded in having Ms Zoe Reiter, a senior programme officer of Transparency International come especially for the occasion to make a presentation. Ms Reiter used the occasion to launch formally the Transparency International’s 2011 Corruption Perception Index (CPI). She did not bring good news.

Guyana falls
The CPI ranks countries according to their perceived levels of public-sector corruption using a simple form of indexing to arrive at a score ranging between 0, perceived to be the most corrupt, and 10, perceived to be the least corrupt. The 2011 index draws on different assessments and business opinion surveys that are carried out by independent, reputable institutions. The surveys and assessments that are used to compile the index include questions which relate to the bribery of public officials, kickbacks in public procurement, embezzlement of public funds, and questions that probe the strength and effectiveness of public sector anti-corruption efforts.

Guyana was first included in the CPI in 2005 and in 2010 was ranked at number 116. It plummeted to 134 this year. By comparison our Caribbean neighbours were ranked as follows:
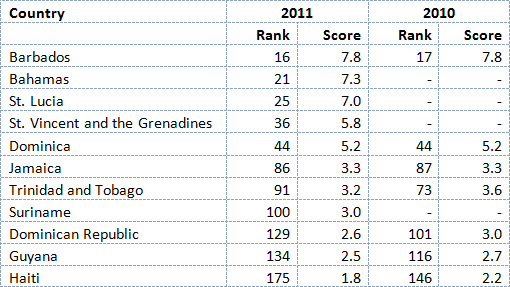
Three of the Caribbean countries are included for the first time: the Bahamas, St Lucia, St Vincent and the Grenadines, and Suriname.

Not wealth nor size but systems
Wealth seems no easy antidote to corruption; some relatively rich countries, including Russia, fall at the bottom of the global league table. Meanwhile, some of the world’s poorer states do comparatively well: Botswana, Bhutan, Cape Verde, and Rwanda all appear among the 50 “cleanest” countries.

Nor is size a major issue either. Many of the smaller island states are in the top half of the corruption ladder while many larger countries are in the bottom half. What seems clear is that those countries with strong systems, independent institutions, modern laws and effective enforcement are likely to be at the head of the line.

New Zealand, a country that has shown a willingness to help Guyana develop systems for better parliamentary governance, occupies the top spot with a score of 9.5 followed by Finland and Denmark. The countries that occupy the bottom ranks in the index are Somalia, North Korea, Myanmar and Afghanistan, which are helmed by unstable governments and conflicts.

Jagdeo’s basket
In terms of corruption, the final year of the Jagdeo administration was not a good one for Guyana or for the PPP/C government. It was dominated by scandals surrounding persons high up in the administration being associated with deals involving state lands, containers, and shady characters. We saw too, the continued inability of the government to bring into operation the Public Procurement Commission, a failure that allows Cabinet to have the final word in contract awards. And it was too the year in which the excesses of the Former Presidents (Other Benefits and Facilities) Act were put under a harsh spotlight and the misuse of state resources for partisan purposes assumed new heights.

It is difficult to tell whether those revelations had any impact on Guyana’s decline but the news confronted Mr Jagdeo’s successor President Donald Ramotar, with both an obligation and an opportunity to establish the first marker on his administration’s attitude to corruption. As stated above, Mr Ramotar delegated that role to his Finance Minister and the abrasive Ms Teixeira. If it was intended to be a clear signal for change, Dr Singh failed both in substance and in style, alienating many if not the entire audience. It is unlikely that if Dr Singh appreciated the significance of November 28, 2011 or the concerns sweeping the world about corruption, from India to the EU countries, Brazil and Russia, that he would have been so hubristic in his reaction to responses and questions from the floor.

Missing the message
Dr Singh might have missed too that Transparency International (TI) chair Huguette Labelle recently pointed out that, “This year we have seen corruption on protestors‘ banners be they rich or poor. Whether in a Europe hit by debt crisis or an Arab world starting a new political era, leaders must heed the demands for better government.”

One wonders how someone as bright as Dr Singh could fail to understand that to continue doing exactly as he did under the Jagdeo administration was neither an option nor wise.

In what was programmed for a 15 minute presentation, Dr Ashni Singh spent no less than forty minutes in a criticism of the methodology used by Transparency International in constructing the CPI and in telling the overseas guest and the diplomatic community about the unrecognized and unacknowledged efforts by the PPP/C administration to deal with corruption. It was all about the significant changes to the constitution during the Jagdeo presidency, the many select committees of the National Assembly, the best Procurement Act in the world and the tremendous strides made in the Audit Office.

Dr Singh seems to have ignored the logic that if the methodology is weak for one it is no different for the others, and that whatever he may think of the CPI it is closely watched by investors, economists, and civil society campaigners and the international financial institutions. He might have noted too the direct comments from the head of the European Union that the EU as a major donor to Guyana is paying close attention to how concerns about corruption are addressed.

The future, not the past
From the floor I pointed out to the Minister that three months ago Ms Gail Teixeira had regaled a TIGI launch ceremony with the same information but only in a slightly more abrasive manner. For the majority in the audience, those acheivements were about the past while their interest was in the future. In other words, the current interest is whether the Ramotar administration would treat with corruption any differently. For Dr Singh – and I guess he intends for all of us – the future would be a continuation of the work-in-progress.

Perhaps Dr Singh’s most ironic and astounding claim was the enhancements in the Audit Office and the number of staff they now have. It was a case of ‘never mind the quality, feel the width.” I could not publicly and in that forum remind the Minister of the lack of appropriate qualification of the holder of the top post in that office, the unprecedented lack of independence of the holder of the second most top post and the fact that both were acting in their positions!

Maybe he should speak with Greg Christie, Contractor General of Jamaica which scored 3.3 out of 10. Mr Christie called on Jamaicans to demand major changes or face stagnation and in language that resonated in the southern-most Caricom state, Mr Christie said, “It should now be abundantly clear to all Jamaicans that unless they demand monumental changes in the country’s existing moral, ethical and legal anti-corruption codes, and in its approach to the co-joint issues of transparency, accountability and good governance in the administration of the affairs of the Jamaican state, 10 years from now we will still be at the same place, talking about the same things.”

So what can we do? Here are some obvious steps:

1. re-constitute the Integrity Commission;

2. constitute the Public Procurement Commission;

3. revamp the Audit Office, replace the head and deputy head, remove the Office from the financial controls of the Minister of Finance and modify the processes and procedures by which it conducts its audits;

4. strengthen the Public Accounts Committee of the National Assembly, widen its mandate and ensure that it is properly resourced and has access to independent professionals;

5. repeal and replace the Access to Information Act with one that brings in sunlight and that provides for protection for whistleblowers;

6. introduce anti-corruption legislation;

7. replace the expired Commissioner of Police and set up a strong anti-corruption unit in the Guyana Police Force;

8. punish in the court without fear or favour showing no mercy, those who feel it is their right to steal from society.
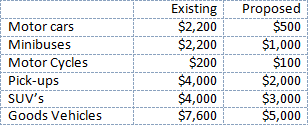
Bisram got it wrong

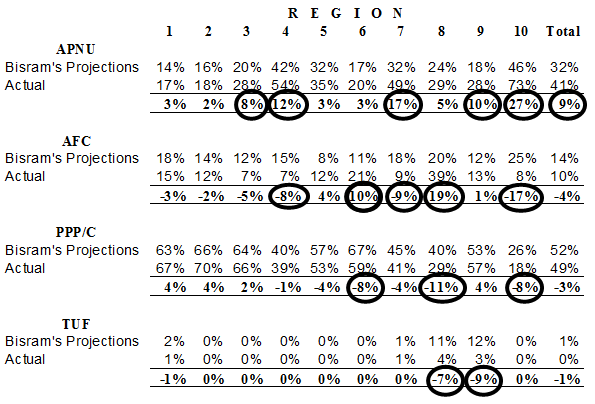
Now that some of the elections’ debris seems to be settling, I thought it might be a good time to review Vishnu Bisram’s pre-elections poll findings and compare these with how the electorate actually voted on November 28. In the following Table, I set out the share of the votes by region, as well as and the overall share of the votes which according to Mr Bisram would be in favour of the four parties contesting the elections. The table then compares these with the actual voting as reported by Gecom and highlights the significant differences.

Despite having a margin of error of 6% – high by any polling standard – Mr Bisram got it wrong in seven (3,4,6,7,8,9 and 10) of the ten regions. For good measure, his poll also had the overall result for the APNU off target by 9 percentage points. That is an error rate of 70%! As readers would note from the table, these are by no means small percentages and in six of the seven regions where he was wrong by more than the margin of error, the difference in percentage points was in the double digits. Indeed in those cases, the error ranged from 10% to 27% percentage points.

These huge margins are rare for any credible pollster and may vindicate those who have criticised NACTA and Mr Bisram for less than professional, objective and impartial polling. His last pre-election poll carried only in the Guyana Chronicle not only caused Mr Bisram’s reputation considerable if irreparable damage but quite possibly adversely affected the PPP/C’s electoral success as well. One day before the elections, the Guyana Chronicle converted his poll and its margin of error into a “landslide” for the PPP/C with APNU and the AFC trailing.

Maybe Mr Bisram should take some time out to review his methodology and in future offer to Guyanese polls that are more reliable, objective and useful.

Finally, while Mr Bisram got it wrong, the voters got it right. They have shown that no one party has a lock on the electorate and for the first time have given the country shared governance between two major arms of the state. I am more than just hopeful that our politicians will rise to the occasion and we will have balanced growth and development over the next five years.

NIS buys Clico building for $600 million

Introduction
At a time when the National Insurance Scheme is experiencing the results of more than two decades of bad governance it has just dished out some $600 million to buy the CLICO building on Camp Street. That building was the single most valuable asset of the failed giant insurance company which was placed first under judicial management and later ordered by Chief Justice (ag) Ian Chang after he found that information available to him in 2010 pointed “unerringly” in the direction of its insolvency. The Chief Justice appointed Bank of Guyana Governor Mr Lawrence Williams as liquidator of the company but in keeping with the law Mr Williams was appointed in his personal capacity.

The acquisition is an interesting transaction. On the one hand the building is one of the largest buildings in Georgetown and the transaction is the single largest real estate transaction ever entered into by the Scheme. Yet but not surprisingly, the board of the NIS headed by Dr Roger Luncheon has not made any statement on the matter. With one old but historic church site sold in Regent Street for $500 million dollars the NIS might have thought it was getting a fancy building at a steal.

Shortly after the danger signs appeared in February 2009, a report on the net assets of the company showed the building as CLICO’s single most valuable asset. According to the report done by a local accountancy firm the building had a going concern value of $1.5 billion and a liquidation value on a best case scenario of $1.112 billion and under a worst case, $750 million. So $600 million must be a good price for any buyer.

Bigger building
Hopefully the Liquidator can explain this and whether he sought out the widest possible prospects to ensure that he obtained the best possible price as his fiduciary obligations would require. The price at which the Liquidator sold the property ought to be of some concern to the creditors of CLICO since it is out of the pool of proceeds that they are paid. Fortunately for the Liquidator and despite several possible causes, no challenge has been raised in relation to the liquidation of CLICO.

The building which dominates Camp Street seems to have been built without any serious consideration for cost, and indications are that it would be extremely expensive to maintain. Perhaps in making the acquisition decision the directors might have felt that the existing head office built decades ago is no longer adequate to house the staff and records and cater for the persons who visit there daily.

Or perhaps it wants to consolidate its Georgetown operations which are now housed in three locations, hopefully leading to greater efficiency and economy. In that case, our pensioners and persons attending the NIS office for medical and other reasons will have to accustom themselves to use elevators!

Bigger issue
If the NIS moves offices it will then have to consider what it would do with the existing buildings and whether there is a market for them. If that turns out not to be the case, the NIS would regret its $600 million dollar decision in addition to other costly decisions and transactions it has had with CLICO. For example, as at December 31, 2009 the NIS had more than $5.8 billion invested in CLICO which it seemed most unlikely to recover, not withstanding the bravado of Mr Jagdeo that the “NIS would not lose a cent.”

And in his own peculiar style Dr Luncheon had assured the auditors during the course of the 2009 audit that “the Board of the National Insurance Scheme wishes to advise that it has noted the undertakings made by the President concerning the recovery of NIS investments in CLICO.

The Board is also mindful of the unanimous Parliamentary Resolution guaranteeing state support for recovery by NIS of its investments in CLICO. As such, the Board has the utmost confidence that the undertaking would be honoured and the investments of NIS in CLICO will be recovered.”

With recent parliamentary developments I do not think the matter will be that simple. The end of the Jagdeo presidency allows for all the questions that have gone unanswered for nearly two years to be answered fully and truthfully. It would be sad indeed that the NIS should be one of the first casualties of the newly configured National Assembly.

Clearly, Jagdeo’s undertaking is not worth a cent and the opposition controlled Assembly will no doubt demand a quid pro quo: an investigation into the collapse of CLICO including the unlawful transfer of money abroad, the relationship between Jagdeo and CLICO and its CEO and whether there was impropriety in the use of $1.5 billion the company received from the New Building Society to which it sold the bulk of its investments in the Berbice Bridge Company bonds.

More of CLICO and the NIS
Now let us return briefly to the liquidation. CLICO’s principal asset is now well and truly sold for $150 million less than the worst case fire-sale price. So that those larger investors who were hoping to get some more out of CLICO might just have experienced that sinking sensation which we have all felt at some time. Their situation is at least $150 million worse but even that to the NIS as a creditor of CLICO is chicken feed.

For several years, the NIS has been engaged in some quite interlocking, if not incestuous relationships with CLICO. It had lent CLICO and Hand-in-Hand Insurance Company tons of money at modest interest rates which they then invested in the Berbice Bridge Company at quite attractive rates of interest. Indeed CLICO was such a big investor that its CEO and Director Ms Gita Singh-Knight was hand-picked as the Chairperson of the Berbice Bridge Company Inc.

But there may be a bit of good news. As at the date of the net assets report referred to above CLICO is shown as an investor in the Bridge Company to the tune of $605 million made up of $400 million in Subordinated Loan Stock, unpaid interest of $89 million and short-term loans of $116 million.

There is no indication whether Mr Williams the Liquidator has sought to liquidate those funds or call in the unpaid interest. If not that is a good small piece and some consolation.

Conclusion
Finally, I saw a newspaper article refer to the payment of the building to be by way of a set-off. In my view this is not permissible under the law but then the liquidation of CLICO has had improper interference from then President Bharrat Jagdeo which was hardly consistent with the law.

The reason for set-off not being available is that it would amount to a preference to the detriment of the 39 policyholders who at the date of cessation of business had balances in excess of $30 million but who were paid up to a maximum of $30 million only.

I am sympathetic to the new members of the National Assembly whose task is almost as huge as the cleaning of the Augean stables.

Berbice River tolls can be substantially reduced

Introduction
The Demerara Harbour Bridge is vested in and operated by a public corporation, while the Berbice Bridge was built and is operated by the Berbice Bridge Company Inc, a private company under a Build, Operate and Transfer Agreement. The Demerara Bridge was constructed under the Burnham administration in 1978 and vested in a public corporation in 2003. The toll for a motor car to cross the Berbice River is $2,200. The toll to cross the Demerara River is $100. There does seems something quite inequitable in such an arrangement and one wonders why a government that draws so much of its support from Regions 5 and 6 would subject its residents to the kind of high fares that the private company charges.

By now, everyone is aware that the country has long come out of an IMF arrangement and even if the bridge was constructed when Guyana was under such an arrangement, the Jagdeo administration was still willing to defy the IMF and World Bank to build the ill-fated Skeldon Sugar Factory, and the stadium. And we have been willing to invest in a $3 billion fibre-optic cable, a specialty tourism hospital and a hotel.

Ghost town
Since the bridge opening in late 2008, business in New Amsterdam has fallen off dramatically. Understandably, if not entirely justifiably then, the local business community is attributing many of the problems facing them first to the location of the bridge and second, to the high tolls charged by the Bridge Company. When I met last Thursday with members of the Berbice business community they complained about the refusal of Chairperson of the Bridge Company Ms Geeta Singh-Knight and her directors to give them an audience and to discuss the effect of the company’s high tolls on their businesses. Indeed, they pointed out the irony that businesspersons from Georgetown are now doing better and brisk business in Berbice, to the detriment of the Berbice businesses. According to the persons I met, the effect of siting the bridge at D’Edward has made New Amsterdam into a ghost town at night.

But notwithstanding their arrogance and insensitivity to Berbicians, the directors – all of whom are Georgetown-based – can do nothing about the location of the bridge. That, according to both government critics and observers, was loaded with political considerations. If the bridge was placed further upriver, traffic would have had to pass through unfriendly villages and the town of New Amsterdam which has never had a warm relationship with the PPP/C. And this was before President Jagdeo described its Mayor in language most inappropriate for Business Page.

The government on the other hand argues that politics had nothing to do with it. That it was about cost. That if the bridge was built further upriver, the capital cost on new roads and the likely logjam in New Amsterdam would have been intolerable. In any case those arguments are moot now: the bridge is where it is and there is nothing the directors or anyone else can do about it.

Addressing the high tolls
Ever since October 16, when in the Business Page column I reviewed the Bridge Company’s annual return and the 2010 financial statements, I have been studying how the second issue – the high tolls – can be addressed. I am more than ever convinced that the legal structure, nature of ownership and the financing model are the cause of the high tolls. The 2010 audited financial statements show that the company had assets of $8.9 billion of which only $400 million was put up by equity shareholders with the remaining $8.5 billion coming from high cost, interest bearing debts, namely, 950 million Preference Shares with a return rate of 11% and redeemable at increasing percentages after year fifteen; Subordinated Loan Stock – $1,250,000,000, repayable 2026; Bonds Tranche 1 – $3,050 million at 9% maturing 2013; Bonds Tranche 2 – $2,525 million at 10% maturing 2017 and Loans – $450 million.

The result is that the company has to pay over $800 million annually in interest alone. Because of the business model and financial structure of the Demerara Harbour Bridge Corporation, that corporation has no debt financing and therefore no interest cost. A similar model for the Berbice Bridge would therefore save upward of $800 million which can then be applied to lowering the tolls.

Savings
My recommendation is for the government to buy over the debts paying by way of Treasury Bills at lower rates of interest to reflect the lower risk of government paper compared with private sector loans to a company whose projections had shown it would be a high risk investment. To the question of why the government should assume the debt, the answer is why should Berbicians be subjected to a model that is different and more costly than that in Demerara?

Some even argue that road users pay no toll and it is unfair for those who live in an important region of the country to have to bear costs which others do not have. The government pays for the roads often with borrowed funds so there is nothing unusual or burdensome about the government carrying the cost via the public accounts.

Readers of this column would also be aware that the investors in the company enjoy the widest range of tax concessions paying no corporation tax, income tax and withholding tax while the company enjoys additional exemptions from customs duty, VAT, etc. In public finance, tax concessions are treated as a cost so the government has a saving, albeit a non-cash one.

Legal structure
The other problem lies in the legal structure and the nature of ownership of the Berbice Bridge Company. It is a private limited company incorporated under the Companies Act 1991 and operating under a Concession Agreement for twenty-one years. This means that all the company’s investment in the bridge has to be recovered within that period, for which the clock is already running. In other words, since the right to operate the bridge ends in twenty-one years, the investment must be written off over that period. That gives an amortization charge of roughly $500 million. Again, if we look for a comparison with the Demerara Harbour Bridge we note that in the 2003 Act creating the corporation, the bridge was vested at a nil value. Apparently the Demerara Harbour Bridge Corporation does not file its annual report and accounts in the National Assembly and I am therefore unable to say whether, subsequent to vesting, it revalued the bridge and has been taking depreciation on it.

My recommendation is that after paying the investors, the government should vest the bridge in a new entity, at nil or at a value lower than the cost. This would allow for a substantially reduced depreciation or indeed none at all, with the savings going to the users of the bridge. An alternative suggested by my partner is vesting at full cost but for the government to make an annual grant to the entity equivalent of the depreciation charge. That seems eminently sensible, since commercial entities like the Chronicle and NCN are given annual subventions with much less justification.

Putting aside money
The other point of considerable significance arises out of what I referred to earlier: the duration of the Concession Agreement which incidentally has not been tabled in the National Assembly or ever released to the public. It means that apart from the annual interest, the Berbice Bridge Company would have to repay all borrowings and preference shareholders at agreed times but no later than at the end of the concession period.

What the Bridge Company requires is to set up a sinking fund account into which it places sufficient cash to ensure that it can meet its obligations as the repayment of the borrowings becomes due. For example, in another two years, the company has to find $3,050 billion to pay the investors in the Tranche 1 Bonds, on pain of penalty. The company clearly will not be able to do so (it had practically no cash balance at December 31, 2010), and will have to roll over the debts. Four years later, Tranche 2 of $2,525 million becomes due and it will also not be able to meet those obligations.

As the end of the concession period approaches, the company will find increasing difficulty in persuading anyone to lend it any money, let alone billions of dollars. From the October 16 Business Page, readers would have noted that the government was forced to waive hundreds of millions of dollars on its preference shares, just so that the company could pretend that it was meeting its other obligations. In fact it was only able to do so by the very dubious and possibly illegal waiver by the government.

Would the government have to waive that more than one hundred million due to it every year and would it also waive the redemption of the preference shares which become due in three years after the second tranche bonds? The Berbice Bridge Company seems to be a walking insolvent company and shielding it from that embarrassment is not only financially sensible but will allow any successor operator to charge considerably lower tolls and yet be solvent.

Looming clouds
In its present form the company requires about $1550 million annually to meet its annual operating costs, the interest and dividends payable to investors, and future loan obligations. In 2010, its total income was $1,115 million, a shortfall of $435 million. The company’s only hope for survival is that traffic would increase by an improbable 50%, or that it can increase tolls by that amount. That would surely be unacceptable, even for Berbicians.

Ramon Gaskin had predicted this situation more than five years ago when Winston Brassington was trying to twist the arm of the New Building Society directors to invest $2 billion in the bridge. The directors agreed with his assessment and it was only when Dr Nanda Gopaul became Chairman that the NBS bought over some $1.5 billion dollars in bonds held by the sinking Clico. I do not believe that we have heard the last of that investment.

Conclusion
Despite substantial subsidies, the bridge is uneconomic for the body of investors as a whole, and most especially the government in the form of exempted taxes running into further hundreds of millions of dollars and in waivers of Preference Shares Dividends. The high cost necessitates an unbearable burden on the users of the bridge in the form of tolls.

Even at, or because of the high tolls, the company will continue to have significant shortfalls to cover annual expenditure and current and future debt obligations. In the medium to long term the company would only be able to repay loans by further borrowings and would be insolvent, ie unable to pay its debts at the time of its contractual handover. The cost of the bridge to users and especially Berbicians is both economic and social.

My recommendation for reducing the high debt cost of the Bridge Company is stated above. Additionally, instead of paying NICIL (or one of its satellites) for the $950 million in redeemable shares it holds, these can be converted to ordinary shares which will attract dividends.

Organisationally, I also recommend the establishment of a national Bridges Authority out of the separate entities. This single entity will own and operate all publicly owned bridges in Guyana enjoying the benefits of shared expertise and management.

Finally, I recommended in my presentation to the Berbice businesspersons the following toll charges:

My numbers indicate that the new entity will make in one year a surplus of $79 million at the proposed tolls, if the government, having bought out the investors, vests the bridge in the new entity at 50% of its cost. If it is vested at an even lower value the tolls can be reduced even further.

Whatever the result of the elections they will not have been fair

Parliament was prorogued in late September, meaning that we now have no parliament and the passage of new laws including those for incurring of new debts must await the next parliament. However, to ensure that the wheels of government do not grind to a halt, the constitution provides for the executive, including the president and the cabinet, to remain in office until a new government is installed. The government meanwhile assumes a holding mode, sometimes loosely described as a lame duck government.

Our constitution does not specify, or indeed restrict, the powers of the government during this holding period. That does not mean the government can do as it pleases. Indeed what it should do is to follow convention and good practice and limit its actions, decisions and expenditure to what the National Assembly approved before prorogation. Accordingly, the decisions they should make and action taken should be restricted to routine, operational matters.

It would not be appropriate for example for the government to enter into a new international treaty or to make a decision on matters that would require parliamentary approval, whether in the form of authorisation or the provision of finance. I understand that the constitutions of some countries limit the actions such holding governments can take, thus making it unconstitutional for them to do the kinds of things that have become routine under the increasingly lawless PPP/C.

The thinly disguised Cabinet Outreach, outboard engines and fertilizer of 2006 are modest compared with the multibillion agreements we have been hearing about since the announcement of elections. A few days ago we learnt from Jamaica that Jagdeo has signed a secret deal with the Chinese for an investment of $27 billion on the Timehri Airport, and from the local press that he is borrowing $4 billion from India for a specialty hospital, and is committing several billion dollars for an overpriced Marriott Hotel.

We have become so accustomed to this lawlessness that we simply dismiss Mr Jagdeo’s actions as further cases of his routine violations of the constitution, some of which concern the protection afforded by the constitution. These include the appointment of an Ombudsman, the Public Procurement Commission and the integrity of the Consolidated Fund and the Contingencies Fund.

There are two important consequences to these actions: whether it is proper for the Jagdeo administration to tie the hands of the successor government; and the impact of such actions on the elections. The first touches on the constitutional issue of whether a successor government (PPP/C, APNU or AFC) should consider itself bound by these reckless decisions. Unfortunately Mr Donald Ramotar appears to be a party to most of the recent excesses and would seem to be allowing himself little or no room to revisit any of them. It would seem from their pronouncements that the other major parties are committed to revisiting and quite probably rescinding a number of the recent deals, with the Amaila Project heading the list. That could put Guyana on a collision course with investors and tarnish the country’s reputation as an investment destination.

On the issue of the fairness of the elections, I think it would be hard for anyone to conclude that house lots to communities, subventions for Veterans Homes, salary increases to public servants and the disciplined services, the signing of new contracts with major tax concessions and or state borrowings, the payment of discretionary sums from the ruling party office and the opening of miscellaneous facilities by the President and his ministers are not intended to and will not influence the vote. That means the elections – whatever the result – will not be free and fair and one hopes that the Elections Observer Missions are taking note.

Over the last fourteen years I have tried to convince GECOM and the political parties to have some form of campaign finance rules. Mrs Sheila Holder actually tabled a motion in the National Assembly on this. The PPP/C simply stalled. As a result we have neither campaign rules nor restrictions on the use of state resources for party political purposes.

It is a gift for a president who has no sense of constitutional convention or propriety, has no respect for the rule of law, and indulges himself with the belief that he is all powerful.