Canadian auditor’s suggestion that Sharma be appointed Auditor General was tantamount to improper interference in Guyana’s affairs

Mr Deodat Sharma may not be a proper Auditor General but he surely knows how to play the political game. Last week, the Audit Office which he heads hosted a team of two from the Audit Office of Newfoundland and Labrador (AONL) with which the Guyana Audit Office claims a “twinning partnership.” The website of the AONL indicates no such partnership.

I understand from persons who attended a workshop conducted by the two visitors from Canada that one of them actually sought to advance the case for the confirmation of Mr Sharma who for seven years could not be substantively appointed because of lack of qualifications.

Mr Sharma’s lack of qualifications would likely prevent him from being appointed Audit Manager, much less Audit Principal or Auditor General, in the Newfoundland Audit Office.

In my view, the attempt by the Canadian gentleman was insulting, inappropriate and tantamount to improper interference in the operations of Guyana’s national financial watchdog which no Canadian Audit Office would accept and tolerate for itself.

Here are some interesting statistics. The Auditor General of Newfoundland and Labrador is appointed for a 10 year non-renewable term by the Lieutenant-Governor in Council and confirmed by a resolution of the House of Assembly. (Term limit for Auditors General is a common feature in other countries as well, but not in Guyana.) The Newfoundland Office has less than a quarter of the staff of the Guyana Audit Office – 36 compared with 150 – but while 28 of their staff hold professional accounting designations (78%) only 2 or 3 persons (1.33% or 2%) in the Guyana Audit Office are similarly qualified.

In its work, the Office of the Auditor General of Newfoundland and Labrador complies with the professional and ethical standards established by the Canadian Institute of Chartered Accountants. And according to that Audit Office, they adhere to professional codes of ethics and independence standards; exhibit independence in fact and in appearance; and avoid perceived and real conflicts of interest. In Guyana we aspire to and apply low or no standards.

I do not for one moment however believe that it is only because of lack of qualifications throughout the Guyana Audit Office that it has failed so miserably in unearthing the kind of frauds which the reporters from Kaieteur News and to a lesser extent, the Stabroek News, have been uncovering.

Rather, it is because some of those who hold senior positions cannot afford to jeopardise their position or embarrass the Minister of Finance and the government.

It is 0.01%, not 1% – Part 2

Introduction
The events of the past week have been significant and distracting. It started with the sole AFC representative on the Public Accounts Committee not attending one of the most critical sessions of the PAC – ever. In the process and against all the rules of professional ethics, the wife of the Minister of Finance has been elevated to being the key intellect and influence in the Audit Office. That failure by the AFC for which it never even bothered to express regret, let alone an apology and sanction, was followed by the announcement of the renewal of the appointment of Professor Compton Bourne for another three years. Within three days he renounced the extension, leaving the university in continuing shambles. Then came two resignations: one from the CEO of NCN Mr Mohammed Sattaur and the CEO of telecommunications giant Guyana Telephone and Telegraph Company Mr Yog Mahadeo who only hours earlier had been elected Chairman of the Private Sector Commission. And as the Minister of Education proudly announced the results of the Grade 6 examinations, the contract of a top education official was summarily brought to an end, for what the Minister described as “different” reasons. For a small country of barely three-quarters of a million, our capacity for spicy news seems to be boundless.

But let us return to the topic begun last week in which I made the point that the disparity or gap between the rich and the poor – or as Jagan used to describe them, the haves and have-nots – is reaching alarming proportions. I advanced the proposition that nought-point-nought one per cent (0.01%) of the Guyana population owns between 70 and 80 per cent of the private wealth of the country. On the one hand most of these people keep a very low profile: at least in Guyana. One of my seventy-eight held the wedding of his son at Disney in Orlando. Another preferred to take many of his guests to his daughter’s wedding in New York rather than have it in Guyana. The members of this privileged group are seldom seen in the newspapers – not even giving to charity. With helpful attorneys and accountants in their corner they generally feel less insecure giving to the party than the state in the form of taxes.

Trickle down
On the other hand, with no control over or accountability of election funding, the 0.01% know they control the politicians. Part of this country’s unfortunate problem is that none of the political parties or leading politicians has ever expressed any real interest in any but a market-based, trickle-down economic agenda, if at all. If we need any evidence of how the legislators treat the working poor in the country consider the following: for four years, the regulated wage was $100 per hour for several thousands. Thanks to Labour Minister Dr Nanda Gopaul, that was raised to $140 per hour, which is still not enough, but yet the 0.01% grumbled.

President Ramotar had promised and in fact appointed a committee to review the tax laws. That committee never met, never had any terms of reference or any time-table. To the embarrassment of the members, the committee is as good as dead. It is no surprise that the tenure of Mr Ramesh Dookhoo as chairman of the Private Sector Commission has come to an end without anything to show for it in terms of tax reform.

Not theory
As a country we remit or forgive as much in taxes (tax expenditure) as we collect. The Audit Office has quietly dispensed with reporting on these. But they alone are not to be blamed. Think of those MPs for whom the first order of business – and last as the Parliament comes to an end – is their duty-free vehicle. Like the businessmen among the 0.01%, MPs seem not to care about tax reform once they themselves benefit. The most egregious example of course is Mr Jagdeo who signed into law an act that allows him to enjoy for life every known duty concession and complete exemption from any taxes from any source. The man can go into business in newspapers, hotel, airline, tourism or anything else, and will pay no taxes. Not ever.

The obscene income disparity is not a theoretical construct. It is as real as people’s lives. It helps to explain but does not justify or condone the level of crime in our society, the reasons why most women stay in a hostile abusive relationship, migration, low worker morale, poor educational standards and the other ills of society. Our tragedy is that for most, this is the natural order and success is measured entirely in economic terms. Notice how the Education Ministry did not even remark on the absence of hinterland or riverain schoolchildren in the list of those who did well in the recent Grade 6 examinations. The irony is that there are three Amerindian ministers in the government and one former minister administering to the Amerindian votes rather than their needs.

Of the 1%, by the 1% and for the 1%
According to a Vanity Fair article titled ‘Of the 1%, by the 1% and for the 1%,‘ many people look at income inequality and then look away. Like Mr Jagdeo, Dr Ashni Singh would like us not to consider how the pie is divided but the size of the pie. Vanity Fair considers that argument fundamentally wrong because any economy in which most citizens are doing worse year after year cannot succeed over the long haul. Two points made by Vanity Fair seem particularly relevant to Guyana.

First, growing inequality is the flip side of something else: shrinking opportunity. Whenever there is a diminution of opportunity for all, the most valuable assets – people – are not used in the most productive way possible. The second is that many of the distortions that lead to inequality, such as those associated with monopoly power and preferential tax treatment for special interests, undermine the efficiency of the economy. This new inequality goes on to create new distortions, undermining efficiency even further until the system collapses. That surely was the experience and lesson from the Arab Spring, a lesson we are willing to ignore.

It is manifest in our tax system which has all the elements for the creation and sustenance of widening disparity: no taxes on dividends, lower rates on capital gains, massive tax exemptions and widespread tax evasion well beyond the capacity of the GRA and the inclination of the courts.

Progressive (differential) taxation
More than any other tool, the means by which government finances and depletes its treasury by way of tax giveaways affects the societal distribution of wealth. Quoting John Rawls in a Theory of Justice in an article making the case for progressive taxation, Jim Chen of the University of Louisville Law School has argued that differential taxation and targeted spending are the most significant and most effective means by which government can “gradually and continually… correct the distribution of wealth to prevent concentrations of power detrimental to the fair value of political liberty and fair equality of opportunity.”

So that while economists and social planners are convinced that progressive taxation is the most economically efficient means for redistributing wealth, every administration beginning with Hoyte has entrenched a system of taxation that offers opportunities for some at the expense of others.

For sixty years, Guyana had a system of progressive taxation which imposed higher rates as the level of income rose. So for example, the first $25,000 of taxable income was subject to a tax rate of 10% while the next and the next would be taxed at 15%, 20% etc. Progressive taxation was also evident – and still exists – in relation to expenditure taxes with the goods and services used by the poor subject to much lower tax rates than luxury items. That we still have such a structure under the Customs and Excise Tax Acts ought to be a convincing response to those who complain about the administrative difficulties of a progressive system in taxation.

It is perhaps the nature of our society that income inequality and the return of progressive direct taxes are not ever discussed, even among economists. In just about every other country, progressive taxation has endured as the primary engine of redistribution in terms of taxation. Economic policy has been driven by wealth creation for the 0.01% and safety net for the remainder. With all the power and influence residing in the handful, change will not come from them.

Private sector
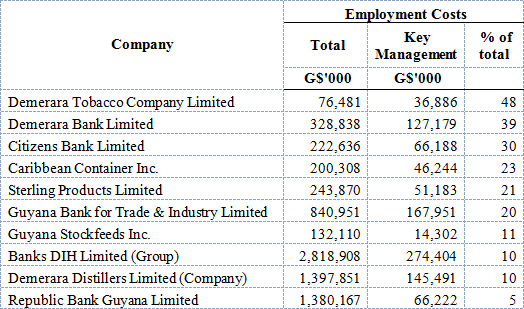
Is the private sector any different? Only the optimist and the charitable will say yes. We have few enlightened employers among us, and even those who try to top up their employees’ remuneration do so at the expense of the treasury by way of under-the-table payments not subject to tax. Contrast that with the following table that shows the share of the total compensation earned by key management personnel – the decision-makers – as a percentage of the total compensation of our major entities.

Source: Annual Reports 2011

And let me say that these do not tell the whole story. The cost of all the perks enjoyed by the few persons falling within this exalted group is by definition not included in their compensation. And let us be fair to Demtoco – it hardly carries on any business in Guyana so has just a few strategic staff. The percentage is also influenced by how the definition of key management personnel is applied with accounting rules becoming increasingly permissive; no longer are companies required to disclose the number of their employees while enjoying much latitude in how they define compensation.

Conclusion
In these past two articles, I explored the inequality of opportunities and income among Guyanese. The best hope for a fairer economic system had rested with President Ramotar who before becoming President had often lamented its injustice. Seven months into his presidency, he has shown no interest in what is now the status quo. For the 99.99%, the unequal distribution of income has deprived them of opportunities. Their hopes lie in a hustle – or migration.

It is time that Guyana has a proper Auditor General

A recent news item in the print media gave the impression that the appointments of four senior members of the Audit Office’s staff have already been made by the long-acting Auditor General Mr Deodat Sharma. That would conflict with the Audit Act under which any proposed appointment first must have the approval of the Public Accounts Committee.

I am concerned that this attempt by Mr Sharma – which not surprisingly has received the support of the head honchos of the PPP/C members of the Public Accounts Committee – is a precursor for himself to be confirmed. Clearly, if the number two position from which he was moved up is subsequently filled, he cannot then step back into it, if and when a decision is finally made to appoint a qualified Auditor General from outside the Audit Office.

Mr Sharma has many handicaps. The first is that he is does not have the qualification to be the Auditor General. Accordingly, he has to rely on – as his key qualified staff – the wife of the Minister of Finance who is responsible for the country’s public finances generally and solely responsible for the Contingencies Fund.

The lack of that competence that comes with professional training has meant that in the six audit reports on the public accounts Mr. Sharma has issued since he was appointed to act, he could do no better than identify two major issues – the tendering procedures for drug purchases and the fact that the drawings from the Contingencies Fund did not meet the qualifying test. But he did not initiate the disclosures – they were continuing developments identified by his predecessors.

In relation to the Contingencies Fund, his reports consistently misquote the law relating to replenishments – conveniently to the advantage of the Minister – and second and very importantly, he does not report findings on the actual payments. No wonder it takes him more than three months to report on a $90 million expenditure in an engagement in which he is taking a lead role. Such an audit should take a pair of reasonably capable junior auditors properly guided two weeks maximum.

Mr Sharma has made lots of promises before. He promised in the 2009 Audit Report to complete before December 2010 value for money audits of the drug purchases by the Ministry of Health and the tender procedures of the government. Before that he had promised audits of the Cricket World Cup, Carifesta and the 2005 Flood Audit. And of course, he had promised that by end of April 2012 he would have completed the $90 million audit of Contingencies Fund, a promise accepted by the National Assembly.

It is impossible to say whether Mr Sharma is as keen to be confirmed in the job as the government is to have someone who hesitates to go after Mr Ramkarran’s “pervasive corruption.” The compensation package now enjoyed by Mr Sharma is the same as that of the Chief Justice and the Chancellor. It would seem that it is as normal for no one to risk giving up such an undeserved package as it is for no government to appoint, even in an acting capacity, a Chancellor or Chief Justice possessing only a para-legal degree.

The Constitution of Guyana provides that whether as a substantive appointment or acting Auditor General, the appointment of the Auditor General is made by the President acting in accordance with the advice of the Public Service Commission.Whether or not President Ramotar wants to deal with corruption, it is time that Guyana has a proper Auditor General.

Once a substantive Auditor General has been appointed, that person working with the Public Accounts Committee can then address the other senior positions and indeed the rest of the staffing of the Audit Office, including the issue of conflict of interest under the Code of Conduct governing accountants.

It is 0.01%, not 1% – Part 1

Introduction
I will start with a simple but stark statistic. My list shows that nought-point-nought one per cent (0.01%) of the Guyana population owns between 70 and 80 per cent of the private wealth of the country. Let me put it in absolute numbers: Nought-point-nought one per cent is equivalent to seventy-eight individuals or one out of every ten thousand persons. And my definition of private wealth excludes state-owned assets and companies such as GuySuCo, Guyoil and Guyana Power and Light. I have excluded as well the foreign owned or controlled companies such as RUSAL, BOSAI, Barama, Scotia and Republic Bank.

In my seventy-eight there are two families but the remainder are all individuals. Except for a couple of cases, there is not a lot of old money around. Current wealth includes new money, drug money and every kind of funny money in-between. Most of the wealth has been accumulated in the last twenty years. This period had its genesis with Desmond Hoyte’s Economic Recovery Programme which began in 1989 and was followed text-book style by successive PPP/C administrations. It seems almost bizarre that this same PPP/C once embraced socialism under the mantra of the defence of the working class. In opposition, the PPP/C’s founder used to rail against the obscenity of the income gap; in government it is a different tune.

With the present meteoric increase in personal wealth has come a scale of income disparity that the powers-that-be find too uncomfortable to discuss, let alone accept. Despite the absence of proper statistics or any published study of this growing problem, the gap between wealthy Guyanese and the rest of our citizens is now a daunting reality. Perhaps the absence of any study has to do with the absence of statistics but surely our economists at the central bank and the University of Guyana can and should make some attempt.

America and Guyana
For years now I have been lamenting the fact that even as we keep talking about tax reform, there are no published data by any of the relevant agencies including the Bureau of Statistics or the Guyana Revenue Authority (GRA) to tell us about sectoral and regional contribution to the tax revenues of the state, the number of persons – companies and individuals – who pay property taxes and capital gains tax, or the income tax paid within bands of various amounts. With the complete computerization of the (GRA) and the kind of information required to be supplied in tax returns, the generation of data for policy-making and research is a matter of the click of a mouse.

It is interesting to note that in that bastion of the free market, the issue of income and wealth disparity is now widely discussed at the highest levels, even in legal journals. I recently read an article tracing the origin of the wealth gap in the USA from the period of the Great Depression to the modern day. In fact, George Bush, whose presidency would be most remembered for the Iraq war and the Bush tax cuts, in 2007 acknowledged the gap, conceding that “income inequality is real.” He was confronted with statistics which showed that the top 1% owned 34.6% of America’s assets and the next 19% held 50.5% of them. Just one-fifth of that country’s citizens therefore controlled over 85% of the country’s wealth. The bottom 40%, by contrast, owned only .03%. The effects of that prosperity gap were harshest on children who were twice as likely as adults to be poor.

Protest
Those inequalities are not as severe as they are in Guyana. Yet policy-makers, academics and American society in the US are responding. Their dissatisfaction gave rise last year to a spontaneous populist protest which began with a few dozen demonstrators pitching tents on Wall Street in front of the New York Stock Exchange which was seen as the epitome of greed and inequality. Soon hundreds that included union activists joined them in a nearby park and the movement spread to a number of cities around the country. The police and the courts were less than tolerant and the Occupy Wall Street Movement as it came to be known fizzled out, but not before it had brought that stark unfairness to the full attention of the American public.

Here are some more statistics from that country. The wealthiest 1% of Americans already has a greater net worth than the bottom 90% based on Federal Reserve data.” Nobel Prize winning economist Joseph E Stiglitz writing in the May, 2011 issue of Vanity Fair magazine was even more dramatic when he said that “in our democracy, 1% of the people take in nearly a quarter of the nation’s income and own 40% of its wealth, the highest percentage since 1948.”

In Guyana the situation is most definitely more pronounced. In the recent period of the reasonably good economic growth during which persons found themselves able to afford a mortgage or a reconditioned car, the disparity may have been felt mainly by single mothers, the unemployed and those on low fixed incomes. But characteristically, as we seem ever so willing to feed the destructive gods of old with the political gridlock of the new dispensation, the economy could soon experience falling investments, a softening of the real estate market, fewer job opportunities and a dampening of consumer demand. Like in the US, the impact will be felt most by those at Cheddi’s “bottom of the ladder.”

How did we get here?
There are a number of reasons for the situation we now face – some good and some bad. There is an old saying that wealth begets power, which begets more wealth. Look how those close to government have managed to move from state asset acquisition to lucrative government contracts with generous concessions, some of which brought income with no taxation, and then on to more acquisitions. Quite a few in my seventy-eight would be included in this category. The increasing ownership and control of resources allowed these persons access to political power and yet more opportunities. With a population of only seven hundred and eighty thousand, very few could amass real wealth other than by way of government contracts. As street smart businessmen, at least some among the seventy-eight readily respond to calls to “help the party” which not only rewards but also protects them.

Then there are a few who by their ingenuity, creativity and entrepreneurial flair have seized upon business opportunities in an environment of little and corruptible regulatory controls and poorly enforced of laws, some of them clearly needing revision. Others have got lucky, such as those in the gold mining sector which has benefited from an extended boom in the gold price internationally while enjoying a tax system locally that was clearly not adaptable to the current era.

Some have had windfalls bestowed on them through the tax system. The first is not only that successive administrations have ignored the important role which taxation could play in bridging the income and wealth gap, but have actually contributed to its widening. Early o’clock Hoyte abolished the Estate Duty, a tax that captured in death what was avoided in life. Hoyte also removed taxation from dividends so that the wealthy in receipt only of dividend income were exempt from tax while the workers were taxed at the standard rate. Hoyte it seems did not see that there was a range of possibilities when it came to estate duty or dividend taxation. To cap it all, Hoyte also abolished the progressive system of personal taxation in favour of what is effectively a flat tax.

Then the PPP/C
Then came the PPP/C. But instead of following their philosophical line and at least reviewing and modifying the massive concessions Hoyte gave, the PPP/C went even further. They added icing on the tax exempt dividend cake by removing capital gains on the disposal of shares in public companies so that that both income and capital gains on shares in public companies are exempt from taxes. The objective of the concession never materialised but the goody continues.

This government also showed evangelical faith in tax shelters covering a range of income. Encouraged by the country’s Double Taxation Treaty with Caricom, our tax system actually rewards off-shore versus local investments and makes many types of income non-taxable. These emphasise that our tax policy needs to be more creative and re-configured to ensure that the average middle-income earner does not pay a higher tax rate than companies. Equity as a canon of taxation certainly does not operate in Guyana.

The absence of equity (fairness) also shows itself by favouring higher paid income earners over the lower paid employees. For example, the law is more likely to disallow a five hundred dollar meal allowance for the junior employee than a five thousand dollar dinner for the senior manager; a two thousand dollar travel allowance to the junior employee than even two fully maintained company cars with driver and all.

Gold-mining as a sector has a very favourable tax regime for individuals – 2% of the gross value of declarations, which is generally thought to be less than half of actual production. If that is the case, miners pay a total of 6% (5% royalty and 1% tax) for the extraction of a non-renewal resource. In construction and agriculture, the government has resisted every attempt to introduce withholding tax in these sectors which always complain about the onerous record-keeping requirement of the laws. If the withholding tax is made creditable, it is up to the business to choose whether or not to file financial statements with the GRA.

Then there is evasion
Unfair though the above may be, they are all legal and on-the-books transactions. But in addition to these, there are a good number of scams which are used to cheat the revenue of the country. In not too few cases, senior level persons use their employed status as a tax front while engaging in more lucrative side interests, including trading with their own companies, dealing with real estate, or carrying on another business. With the Revenue treating such persons as subject only to PAYE, all their other income is tax-free.

Another scam used by employers is to pay a huge chunk of the employees’ emoluments by way of tax free allowances. In one recent case told to me, the allowance was close to twice the salary while the entire payment was effected by cash. In other words, the taxpayers of the country are subsidizing that employer who incidentally is among my 0.01%.

And of course we have the army of self-employed who convert VAT into income by charging their customers but are not paying over the VAT to the Revenue. They know that for all its efforts and intents the GRA is overwhelmed by the army of tax evaders and that the chances of prosecution are very, very low.

Look at yesterday’s announcements of tenders opened. In addition to the closeness of the bids to the engineers’ estimate, note the preponderance of self-employed. They are not risking personal liability for nothing. They know they are safe.

To be continued
Hand-in-Hand Trust and the Brassingtons – Conclusion

Introduction
Today’s column completes a three-part article looking into the operations of this non-bank, deposit-taking financial institution as well as its murky relationship with the brother of a related party. Neither the company nor Mr Winston Brassington has responded to the claim by this column that by virtue of NICIL’s 10% shareholding in the Hand-in-Hand Trust (HIHT/the company) Winston and his brother Jonathan are guilty of using insider information in a substantial share transaction with the company.

It is instructive that all of this has surfaced even as we hear from the US that Rajat Gupta, who reached the pinnacle of corporate America was this week convicted of leaking inside information to his friend hedge-fund manager billionaire Raj Rajaratnam, who is himself serving an 11-year jail term for using insider information. Of course, as we say, this is Guyana where suspected corporate wrongdoings go uninvestigated, let alone prosecuted as we have seen in Globe Trust, Clico, NICIL and others.

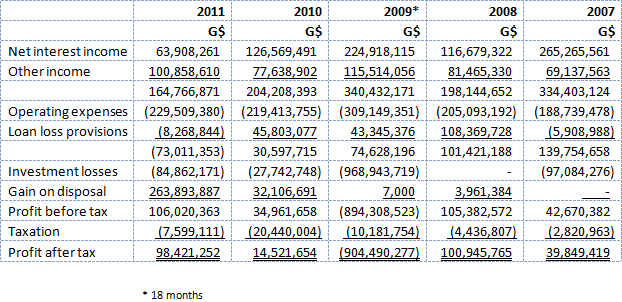
In this concluding part I turn attention to the annual report and audited financial statements of the company Hand-in-Hand Trust Corporation Inc for the years 2007-2011. Here is a summary of the income statement extracted from the audited financial statements.

Over the five years the company’s after tax losses amount to $650 million of which $1,179 million arose from losses on investments, mainly in Stanford Investment Bank and to a lesser extent, Smith Barney, the US brokerage and investment banking house. In fact if a questionable gain on disposal to its parent of its only long-term asset is discounted, the losses incurred by the company over the period would be an astounding $900 million. Whoever decided on the Stanford investment has imposed on the company and by extension the insurance company with a huge loss overhang. Indeed had it not been for the very convenient sale and lease back of its office property, the company would have recorded a pre-tax loss of $158 million in 2011.

There are two reasons for considering the gain questionable: one accounting and the other law. The company entered into a sale and lease back agreement with its majority shareholder of its Middle Street premises. Ignoring relevant accounting standards, the company has failed to disclose the terms of that agreement and dismissed my own query to them for particulars of the transaction.

The balance of probability is that this transaction constitutes a finance lease and accordingly, the gain on disposal ought to have been deferred and recognised over the life of the lease. Recognising the $264 million gain therefore appears improper or aggressive revenue recognition and may have been entered into as a device to improve the company’s capital base for purposes of the FIA.

The legal reason is whether or not the company should have sought shareholders’ approval of the transaction under section 140 of the Companies Act which requires both a quantitative as well as a qualitative test for determining whether or not section 140 applies. With Hand-in-Hand Trust and its parent the Hand-in-Hand group sharing a common CEO – Keith Evelyn – the transaction without approval of the minority shareholders, is less than wholesome.

Other income comprises mainly fees charged for the seven pension plans with a combined balance of $14.9 billion at December 31, 2011, mortgage fees and management fees. On the expenditure side, the company has managed its expenditure well with a 21% increase between 2011 and 2007. There was a spike in the 2009 expenses because the financial statements were for an 18-month period, a change not mentioned in the directors’ 2009 report.

The company’s accounts show regular recoveries of doubtful debts and reversal of diminution in value of properties which have mitigated the other substantial losses incurred by the company.

Compensation
The practice among companies paying comparatively larger sums to its key management personnel is evident with HIHT which paid an average in excess of $1.2 million per month to this group, estimated at more than eight times the average of the rest of the staff. Perhaps more significantly is the 8% per annum interest rate which the company charges its staff.

The financial statements do not indicate the actual rate of interest charged on a director’s (sic) mortgage which at December 31 was a whopping $95.9 million compared with staff mortgages of $7.0 million. According to the notes, “[T]he rates of interest and charges have been similar to transactions involving third parties in the ordinary course of business.”

Balance sheet
The balance sheet too raises some concerns in addition to the treatment of the sale and lease back arrangement. One person very familiar with the measurement of capital adequacy has expressed some scepticism about the company’s computation of the Tier 1 capital adequacy which the accounts claim stood at 31% at December 31, 2011 and total tier 1 and tier 2 capital of 35% and the comparative 14% in 2010. What is certain is that a significant part of an increase would be attributable to the sale of the building which released hundreds of millions in capital reserves. A realised gain is obviously more valuable than one that is unrealised.

Nor do I think that the amount of $778.0 million shown as Term Deposits is properly described since a significant portion of this relates to recoveries in CLICO Trinidad, but which are in the form of bonds maturing several years hence. The related parties balance is a sum receivable from the company’s parent for the sale of the building.

Other risks in the balance sheet include some of the investments in which there has either been a judgment or the filing of legal action. These can result in some losses to the company. On the other hand, if the stock market in the US does improve then some of the Smith Barney losses will be reversed, creating a gain.

The company’s non-accrual loans to total loans has declined from 28.8% in 2007 to 5.2% in 2011, allowing the company to reduce its loan loss provision from 8.4% to 1.5%. That percentage is as good as most other financial business in the country. As Darren Sammy would say, that is a good thing to take into 2012. Deposits have declined from $7,206 million at June 2008 to $5,708 million at December 31, 2011, a decline in excess of 21%. The company also saw the number of pension schemes under management reduced by one during the period.

I must also comment again on the issuing of preference shares and their redemption within one month of the balance sheet date. As noted last week, there is some doubt whether the redemption met the statutory requirements.

Conclusion
In mortgages, the company competes with the New Building Society which enjoys tax exempt status, and the larger financial houses with a far greater income base over which to spread their expenditure. For its trust business to succeed, it will have to attract what are called high net worth individuals. In this regard, its main competitor is probably Trust Company Guyana Limited which has the benefit of being a member of the DDL group which includes two public companies, of which one is a successful bank.

There also seems to be a lot of room for improvement in ethical and governance conduct at the senior level. It was dismissive if not insincere in its response to my written questions while itself having been treated very kindly by the regulator which has not been known for strict insistence on accounting and reporting. Even as the company seeks to expand its income base by entering the lending business, it needs to consider its risk profile and to learn from its Stanford experiences from which it still has not recovered. And at a wider level, the company must be hoping that the high real estate prices can be sustained.

The company faces a challenging future.